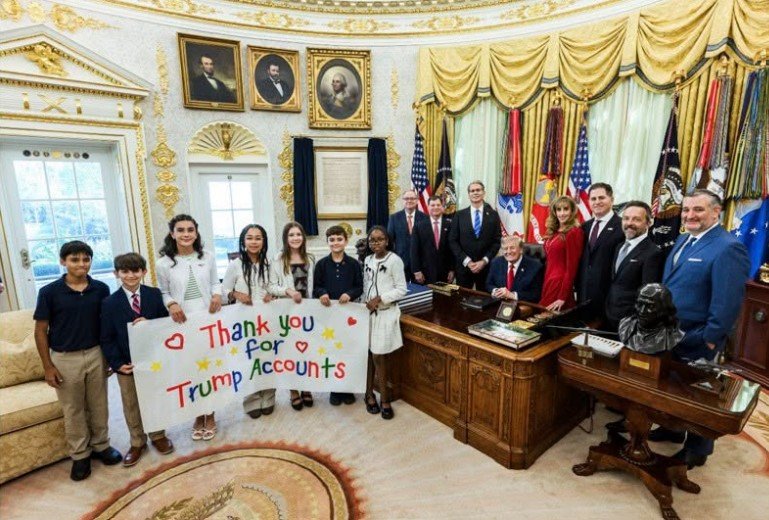
The White House says nearly 70 million investment accounts have been created for children under the Trump Accounts programme, including more than 60 million through automatic enrolment.
In its 7 October announcement, the administration said parents and guardians must still claim their children’s accounts to manage them and enable further contributions.
The figure describes accounts created. It does not mean every child has received a government payment or already has money invested.
What are Trump Accounts?
Trump Accounts are investment accounts with special tax rules, designed to help children build savings over time.
They can receive contributions from families, employers, and qualifying charitable programmes. Eligible children can also receive a one-off federal contribution.
ABC News reported that the automatic enrolment expansion followed the programme’s launch on 4 July.
The accounts provide a way to invest for a child’s future. They do not guarantee financial independence or a particular final balance.
Who qualifies for the $1,000 payment?
The government’s $1,000 contribution has narrower eligibility rules than the account itself.
According to the Internal Revenue Service, a child must be a US citizen born between 1 January 2025 and 31 December 2028, have a qualifying Social Security number and meet the programme’s other requirements.
An authorised adult must request the contribution. A child cannot receive it twice.
Older children may qualify for an account without qualifying for this federal payment. Parents should therefore check account eligibility and payment eligibility separately.
Parents still need to act.
The US Treasury announced the completion of automatic enrolment on 1 October.
It says parents or guardians must claim an automatically created account through the official Trump Accounts app. The process requires identity checks, confirmation of the relationship to the child, review of the child’s information, and acceptance of the account terms.
Claiming allows families to manage the account and enables contributions from relatives, friends, and employers. Eligible families must also complete the steps required to receive the federal contribution.
Contribution limits and access
IRS guidance generally limits ordinary contributions, including employer contributions, to a combined $5,000 annually during the account’s childhood growth period. Certain government, charitable, and rollover contributions are excluded from that limit.
Withdrawals are generally restricted during this period. From the calendar year in which the child turns 18, traditional individual retirement account rules generally apply.
That means turning 18 does not make every withdrawal automatically tax-free.
Why it matters to Africa and the diaspora
African diaspora families with eligible children can benefit from understanding the scheme’s rules. Eligibility depends on the child’s circumstances, rather than African heritage.
Importantly, the IRS lists age and a qualifying Social Security number among the account requirements, while US citizenship is a separate requirement for the $1,000 payment. Families should avoid assuming these are identical tests.
The programme is not a general savings grant for children living across Africa. Families checking their position should use the official programme website and IRS guidance.