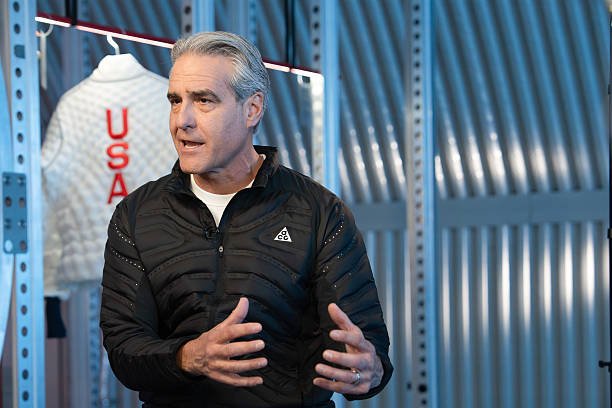
Nike’s latest sales figures and full-year forecast have raised fresh questions about how quickly chief executive Elliott Hill can restore growth to the sportswear company.
Revenue fell 4% to $11.2 billion in the first quarter of Nike’s 2027 financial year, which ended on 31 August. The company expects revenue to fall by a high single-digit percentage across the full financial year. Its shares were down about 8% in early trading on Friday, after the results and forecast gave investors little sign of a near-term recovery. (investors.nike.com, reuters.com)
Hill returned from retirement to lead Nike in October 2024. He has sought to rebuild relationships with wholesale retailers, place more emphasis on products designed for sport, and reduce the company’s reliance on older lifestyle shoes sold at discounts. Nearly two years on, Nike says progress in some areas is being offset by continuing weakness in several of its biggest businesses.
Sales fall despite an improvement in margins
Nike’s first-quarter results show a mixed picture. Revenue declined 4% from a year earlier, while its gross margin rose to 42.8%, helped mainly by lower warehousing and logistics costs. The margin measures what the company retains from sales after the direct cost of the goods it sells. (investors.nike.com)
That improvement did not mean demand had recovered. Nike Direct revenue, which includes its own shops and digital sales, fell 8%. Revenue from wholesale partners fell 1%. The company also recorded lower sales in Greater China and in its Europe, Middle East and Africa region, partly offset by growth in North America. (investors.nike.com)
Nike reported earnings of 48 US cents a share. Its full-year forecast, however, points to a longer wait for sustained sales growth. The company expects adjusted earnings per share of between $1.15 and $1.35 for fiscal 2027, excluding specified restructuring costs. These are projections, not results already achieved. (investors.nike.com)
China and established shoe lines remain difficult
Greater China has become a particular concern for Nike. Sales there fell 26% in the quarter when currency changes are excluded, according to Reuters. The company faces competition from other international and domestic sportswear brands, while its work to change how products are sold and priced online is expected to take several seasons. (reuters.com)
Hill has also identified Nike Sportswear and the Jordan brand as businesses requiring more work. Nike is reducing the number of launches of familiar retro Jordan shoes after years in which an abundant supply made those products harder to sell at full price. Fewer releases may help protect the brand, but they also leave Nike needing fresh products that customers want to buy.
That is why cost reductions alone are unlikely to settle investors’ concerns. Neil Saunders of retail consultancy GlobalData told Reuters that cutting jobs could support profit margins, but would not by itself fix the product and brand problems behind weaker sales. Nike says its performance products are making progress; it also acknowledges that growth there is not yet large enough to offset weakness elsewhere. (reuters.com, reuters.com)
A longer restructuring plan
Nike has announced another overhaul of its operations, known as Pace. It plans to simplify its regional structure, make changes to its supply chain, and reduce costs, including through further job cuts. The company has not said how many positions will go; it expects to begin notifying affected employees in 2027. (investors.nike.com, reuters.com)
Nike estimates that the programme could deliver $2.5 billion in cumulative savings through fiscal 2031. It also expects about $1 billion in pre-tax charges, mainly related to employees, over that period. Those figures are company estimates and could change as the plan is carried out. Reuters reported that most of the anticipated savings are not expected until fiscal 2029 and 2030. (investors.nike.com, reuters.com)
Investors will look for more detail at Nike’s planned investor event in November. The question is whether Hill can show that renewed product development and stronger retail relationships will lift sales, particularly in China and the company’s major shoe lines. The latest results show some improvement in margins. They have yet to show a return to revenue growth.